
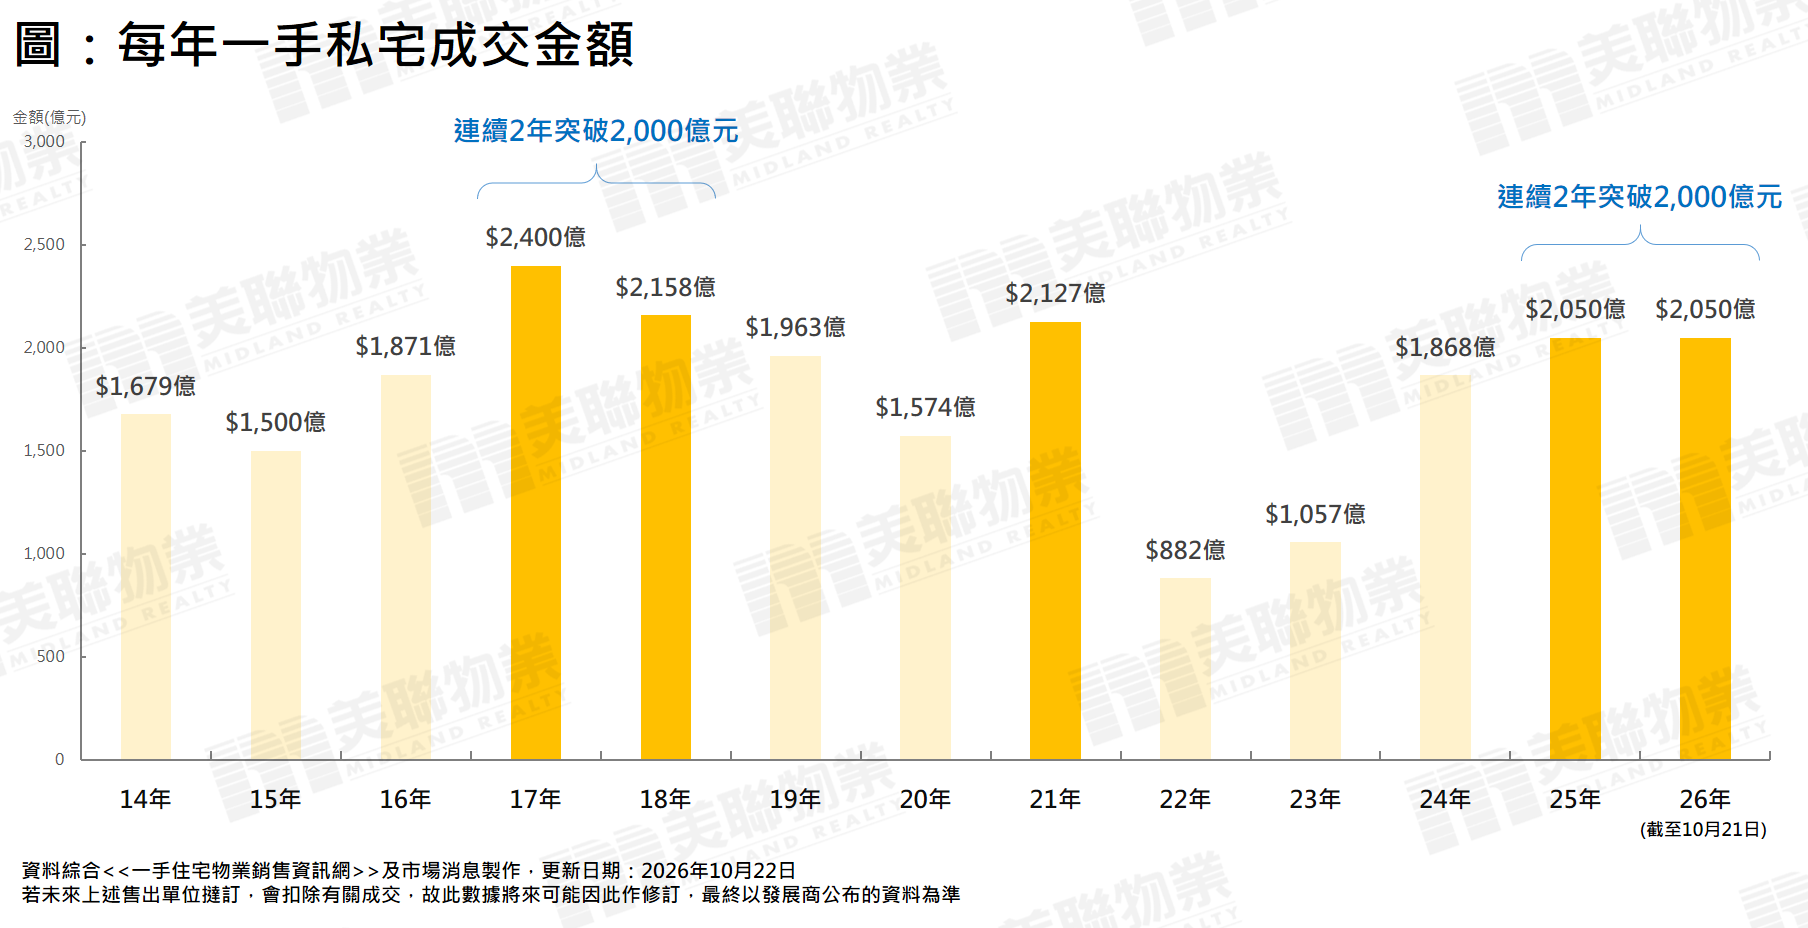
New project transactions are active, with strong capital-raising performance. According to Midland Realty Research Centre’s analysis of data from the “First-hand Residential Property Sales Information Website” and market information, the total transaction value of new private residential properties in Hong Kong this year (as of 21 October) has reached approximately HK$205 billion — matching last year’s full-year level. This means that this year’s record has been matched in under ten months. Notably, the total transaction value of new private residential properties in Hong Kong has exceeded HK$200 billion for two consecutive years — the first time since 2017 and 2018 — reflecting robust capital-raising capability of new projects (see chart).
This year’s transaction value of new private residential properties has already matched last year’s full-year figure, primarily driven by strong performance of mid-to-high-end properties. Data shows that the number of transactions for new private residential units priced above HK$10 M this year (as of 21 October) stood at 4,910 — up about 8.7% compared with 4,515 for the whole of last year — reflecting activated upgrading demand and rising demand for luxury homes.
More than HK$10 M new unit transactions highest in Kai Tak District, accounting for around 24% of the citywide total
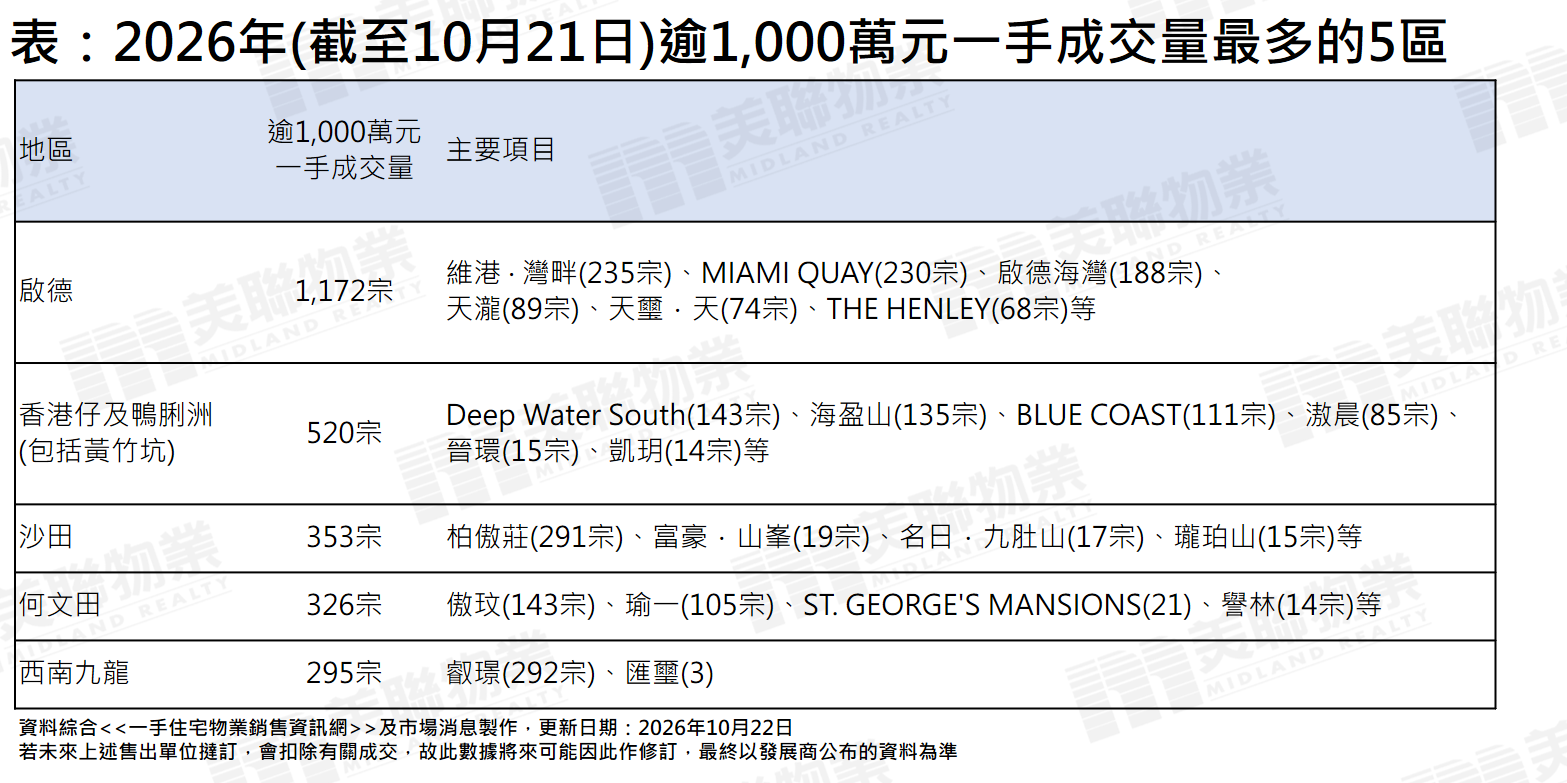
If segmented by region, Kai Tak District recorded the highest number of new private residential unit transactions above HK$10 M this year (as of 21 October), with 1,172 transactions — representing around 23.9% of the citywide total for such units — significantly higher than other areas. Transactions in the district were mainly from projects including Victoria Harbour · Bayfront (235), MIAMI QUAY (230), Kt Marina (188), The Knightsbridge (89), Cullinan Sky (74) and THE HENLEY (68) (see table), reflecting Kai Tak’s status as a major supply and absorption hub for mid-to-high-end new projects, supported by large-scale supply, diverse project types and increasingly mature infrastructure and community facilities.
Hong Kong Island and Ap Lei Chau (including Wong Chuk Hang) ranked second with 520 transactions, mainly from projects including Deep Water South (143), Hoi Ying Hill (135), BLUE COAST (111) and Ao Chen (85) (see table). This area benefits from its traditional premium location on the southern part of Hong Kong Island and railway connectivity, enabling convenient access to commercial core areas such as Central and Admiralty, while large-scale project launches have boosted sales performance of mid-to-high-end units.
Sha Tin District ranked third with 353 transactions, concentrated mainly in The Pavilia Farm (291), an integrated railway station development widely welcomed by the market. High-end properties in the Kowloon Tong hillside area, such as Mount Regalia (19), El Futuro (17) and St Michel (15), also recorded numerous transactions above HK$10 M (see table).
Further reading:
Buying tips
additional costs beyond the down payment | second-hand property purchase process
assignment deed VS gift deed | inheritance of estate property
management fees — more information
Mortgage information
High-loan-ratio mortgages |
Carrie Lam Plan 2.0 |
Mortgage specialist
Latest updates
more midland realty agent transaction cases | property market news | midland realty price index | railway-property market trends
Selling tips
selling cost checklist | selling process
中文版 (【新盤吸金強勁】一手私宅連續兩年破2,000億!上次係幾時?)